12 Best Crypto Savings Accounts in 2026: Earn on Stablecoins
On this page
On this page
- How Does a Cryptocurrency Savings Account Work?
- Top Crypto Savings Accounts Compared
- 1. Binance Simple Earn
- Binance Simple Earn Pros and Cons
- 2. Ledn Growth Accounts
- Ledn Growth Accounts Pros and Cons
- 3. Coinbase USDC Rewards
- Coinbase USDC Rewards Pros and Cons
- 4. Kraken Stablecoin Rewards
- Kraken Stablecoin Rewards Pros and Cons
- 5. Nexo Savings
- Nexo Savings Pros and Cons
- 6. Bitget Simple Earn
- Bitget Simple Earn Pros and Cons
- 7. KuCoin Savings
- KuCoin Savings Pros and Cons
- 8. Bybit Easy Earn
- Bybit Easy Earn Pros and Cons
- 9. Crypto.com Earn
- Crypto.com Earn Pros and Cons
- 10. Bitunix Easy Earn
- Bitunix Easy Earn Pros and Cons
- 11. Sky sUSDS
- Sky sUSDS Pros and Cons
- 12. GRVT Earn on Equity
- GRVT Earn on Equity Pros and Cons
- Risks of Using Crypto-Saving Accounts
- Tips to Choose a Cryptocurrency Savings Account
- Is There Any Tax on Interest Earned From Crypto Savings?
- Bottom Line
- FAQs
- Crypto savings accounts generate returns on stablecoins and other idle crypto assets.
- Flexible accounts keep funds accessible, while fixed terms generally offer higher APYs.
- The best crypto savings account depends on rates, KYC, custody, and withdrawal terms.
- Proof of Reserves provides transparency, and the protection of your funds is a separate question.
- Rates are variable, quota-based, and often depend on balance or membership tiers.
Keeping crypto idle in a wallet can feel wasteful, especially when exchanges and lending platforms advertise interest on the same assets. Crypto savings accounts offer a simple alternative: deposit Bitcoin, stablecoins, or other supported assets and earn a variable or fixed return. The highest advertised APY rarely tells the full story, because rates often apply only to small balances, require locked terms, depend on loyalty tiers, or change by country. This article compares 12 crypto savings products, including custodial, no-KYC, and self-custodial options, on rates, withdrawal flexibility, supported assets, eligibility requirements, and how each platform generates your returns.
How Does a Cryptocurrency Savings Account Work?
Crypto savings accounts let you earn returns on crypto you already hold, a passive way to grow otherwise idle assets. They work in several ways. You can lend Bitcoin, Ethereum, or stablecoins through flexible or fixed-term products, and some platforms pay yield on eligible account balances automatically, with no separate subscription, so the assets stay available for trading or withdrawal.
Behind the scenes, the provider lends assets to borrowers, runs institutional strategies, or shares revenue generated from reserves. Flexible accounts give easier access at variable rates, while fixed terms pay more in exchange for locking funds. Rewards are credited daily, weekly, or monthly, depending on the platform, product terms, and selected asset.
Top Crypto Savings Accounts Compared
While preparing this list, we found many platforms presenting mining, staking, liquidity provision, and other yield-generating products as crypto savings accounts. We limited our selection to services that provide a savings-like experience, where you hold eligible assets and accrue returns over time through flexible accounts, fixed terms, or automatic rewards on idle balances.
We also left out platforms focused solely on staking. Staking lets you earn rewards by becoming a validator, which sits outside our definition of a crypto savings account. With this in mind, here is our list of the top crypto savings accounts for earning yield on stablecoins and other crypto assets.
| Platform | Supported Stablecoins | Savings Type | Advertised annual rate | KYC | Reserve / audit evidence |
|---|---|---|---|---|---|
| Binance | 6+ | Flexible and Fixed | 7.35% | required | yes |
| Ledn | 2+ | Flexible | 8.50% | Required | Yes |
| Coinbase | 1+ | Flexible | Account / region dependent | required | Public financial reporting; not product insurance |
| Kraken | 7 flexible; availability varies | Flexible and Fixed | Up to 6% APY fixed | required | yes |
| Nexo | 2+ | Flexible and Fixed | Up to 11.5% annually | Required | No public live PoR |
| Bybit | 7+ | Flexible and Fixed | 6.24% | required | yes |
| KuCoin | 6+ | Flexible and Fixed | Up to 6% APR on USDG | required | yes |
| Bitget | 6 dollar-pegged assets; USTC separate | Flexible and Fixed | Up to 6.92% APR | required | yes |
| Crypto.com | 4+ | Flexible and Fixed | 2.00% | required | yes |
| Bitunix | 2+ | Flexible and Fixed | Check Easy Earn offer; tiers vary | optional | yes |
| Sky | 1+ | Flexible and Fixed | 4.85% | No KYC | Onchain collateral |
| GRVT | 2 | Flexible | 3.5% base APY | optional | Onchain; underlying-protocol risk |
This comparison uses product terms reviewed in September 2026. Annual rates and supported savings assets are product-specific. APR excludes compounding and APY includes it. Offers change and can depend on your balance, region, membership or lock-up term. Reserve disclosures describe backing at a point in time, and repayment or insurance of an Earn balance is a separate matter. Check the linked product terms before subscribing.
1. Binance Simple Earn
- Best for: Stablecoin selection
- Savings type: Flexible and fixed
- KYC: required
Binance runs one of the most established Earn platforms, with more than 300 assets across flexible and fixed-term products. Its stablecoin selection includes USDT, USDC, EURI, U, USDS, and USDP, with advertised rates up to 7.35% APY. Returns on other assets reach 46.75%, and those products carry far more price and investment risk than stablecoin savings.
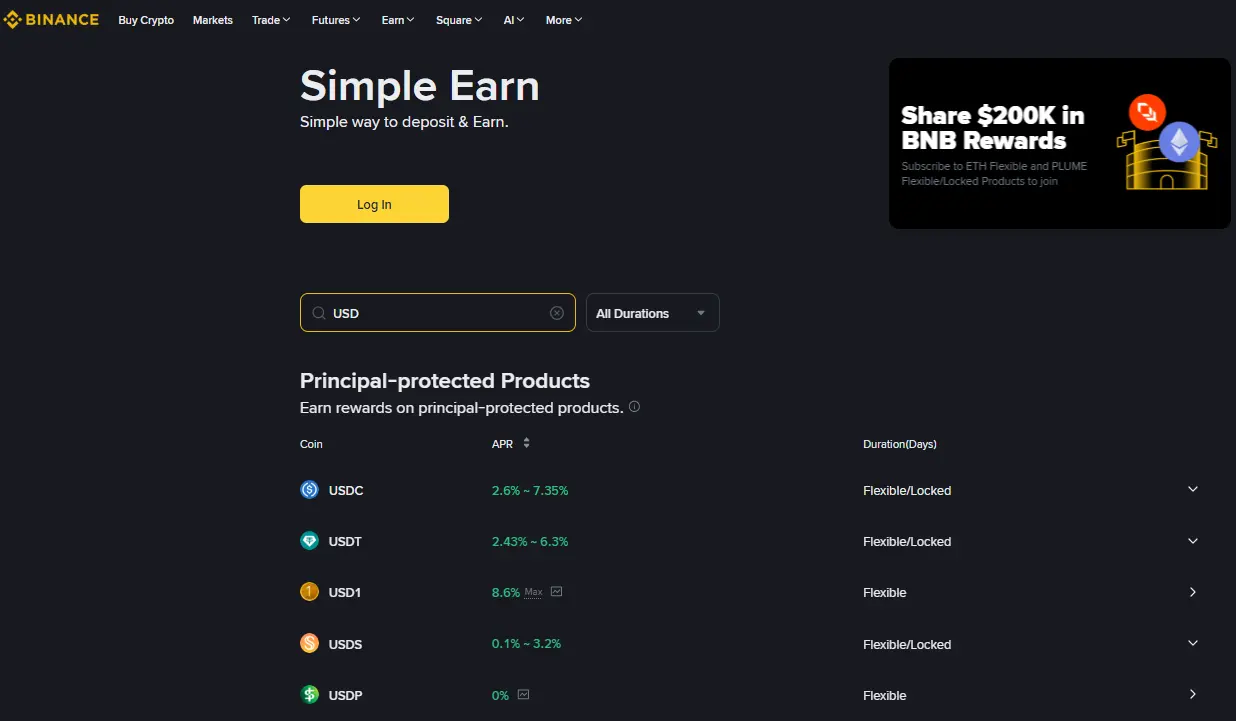
Binance also offers Soft Staking for USDS. Eligible balances accrue rewards automatically while they stay available for trading, a more accessible alternative to locking funds. Its USD Yield Hub includes RWUSD and BFUSD products. You subscribe to RWUSD with USDC and redeem it back into USDC at a 1:1 ratio, with returns supported by real-world asset strategies involving US Treasury bills. Binance also provides liquid staking for returns on other assets, which sits outside the conventional savings-account model.
Binance Simple Earn Pros and Cons
What we like
- Several stablecoins supported
- Flexible and fixed terms
- Automatic USDS rewards
- Public Proof of Reserves
What holds it back
- KYC is mandatory
- Higher rates have quotas
- Product selection feels complex
2. Ledn Growth Accounts
- Best for: Transparent stablecoin lending
- Savings type: Flexible
- KYC: Required
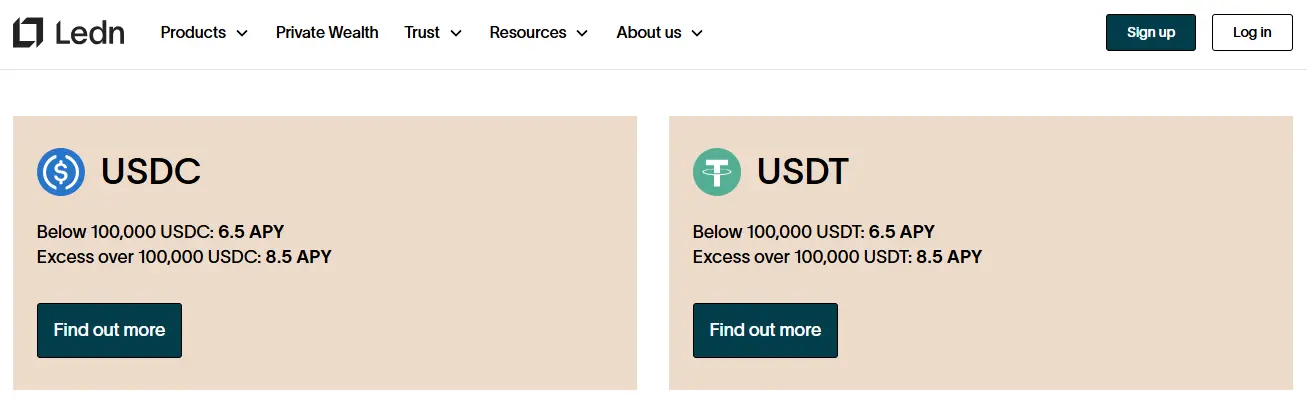
Ledn Growth Accounts are built for earning interest on USDC and USDT. Both stablecoins earn 6.5% APY on balances below 100,000 units, and the portion above 100,000 earns 8.5% APY. There is no minimum balance and no fixed term, and interest is credited monthly in the same stablecoin.
Ledn generates this yield mainly by lending stablecoins through its Bitcoin-backed retail loan book. The loans are secured at a 2:1 collateral ratio, and Growth Account assets are ring-fenced from Ledn’s other business activities. To withdraw or use the funds elsewhere, you first move them from the Growth Account to the separate Transaction Account.
Ledn publishes monthly Open Book Reports and runs Proof-of-Reserves attestations at least twice a year. The attestation covers client liabilities, lending operations, and custodial balances, and clients can verify that their balances were included.
Ledn Growth Accounts Pros and Cons
What we like
- USDC and USDT supported
- No fixed term
- Ring-fenced account structure
- Independent reserve attestations
What holds it back
- Only 2 supported assets
- Interest paid monthly
3. Coinbase USDC Rewards
- Best for: Earning on idle USDC
- Savings type: Flexible balance rewards
- KYC: required
Coinbase pays USDC rewards to eligible accounts holding at least 1 USDC. The rate depends on your country, account type and any promotional offer, so check the rate shown in your account. There is no separate Earn subscription and no fixed term, and your USDC stays available to sell, send, or convert whenever you need it. Rewards accrue daily and are paid weekly. Eligible users can choose rewards in USDC or Bitcoin, as the USDC Rewards terms explain.
Coinbase leaves your USDC untouched and funds the reward elsewhere. Circle keeps the reserves backing USDC in cash and short-term US Treasury assets, which generate income, and Coinbase receives a share of that reserve income through its agreement with Circle and uses part of it to fund USDC Rewards. That is why Coinbase presents the payment as a loyalty reward and leaves the word interest to Circle.
Eligibility depends on location. Users in the United States, United Kingdom, Australia, and Singapore need a Coinbase One membership, and eligible users in other supported regions earn by holding at least 1 USDC.
Eligible UK customers can also use Coinbase’s Instant Access Savings Account, a separate GBP savings product with eligible deposits of up to £120,000 protected by the FSCS.
Coinbase USDC Rewards Pros and Cons
What we like
- No lock-up period
- Weekly reward payments
- Minimum eligible balance of 1 USDC
- Assets held one-to-one
What holds it back
- Only USDC earns rewards
- Coinbase One membership required in some regions
4. Kraken Stablecoin Rewards
- Best for: Flexible and fixed returns
- Savings type: Flexible and fixed
- KYC: required
Kraken Stablecoin Rewards lets eligible users earn simply by holding supported stablecoins in a Kraken or Krak account. Once Stablecoin Rewards or Auto Earn is enabled, returns accrue automatically in the background. There is no minimum balance, holding period, or program fee, and the assets stay available for trading, withdrawal, or transfer.
Flexible rewards cover USDG, USDC, apxUSD, USDe, RLUSD, tokenized GBP, and QCAD, with the selection varying by region. Standard users get lower base rates. Kraken’s September 17 rate schedule lists Kraken+ rates of up to 4.50% APY on USDG, 4.00% on USDC, 3.75% on RLUSD and 2% on QCAD, subject to regional eligibility, and the rates are variable.
Kraken also introduced Fixed Rate Rewards in September 2026. You lock USD, EUR, USDT, USDC, or USDG for 3, 6, 12, or 18 months for a fixed return of up to 6% APY under its launch terms, and those funds stay committed for the selected term.
Kraken Stablecoin Rewards Pros and Cons
What we like
- Several stablecoins supported
- No flexible-account minimum
- Assets remain accessible
- Fixed rates available
What holds it back
- Higher rates require Kraken+
- Fixed funds remain locked
- Availability varies by region
5. Nexo Savings
- Best for: Higher stablecoin rates
- Savings type: Flexible and fixed
- KYC: Required
Nexo provides a crypto savings account for USDT and USDC through flexible and fixed-term plans. Flexible Savings credits interest daily and keeps funds available for redemption. Nexo’s current USDT page advertises annual rates of up to 11.5%, with the higher rates on fixed terms, and your account shows the rate and term that apply to you.
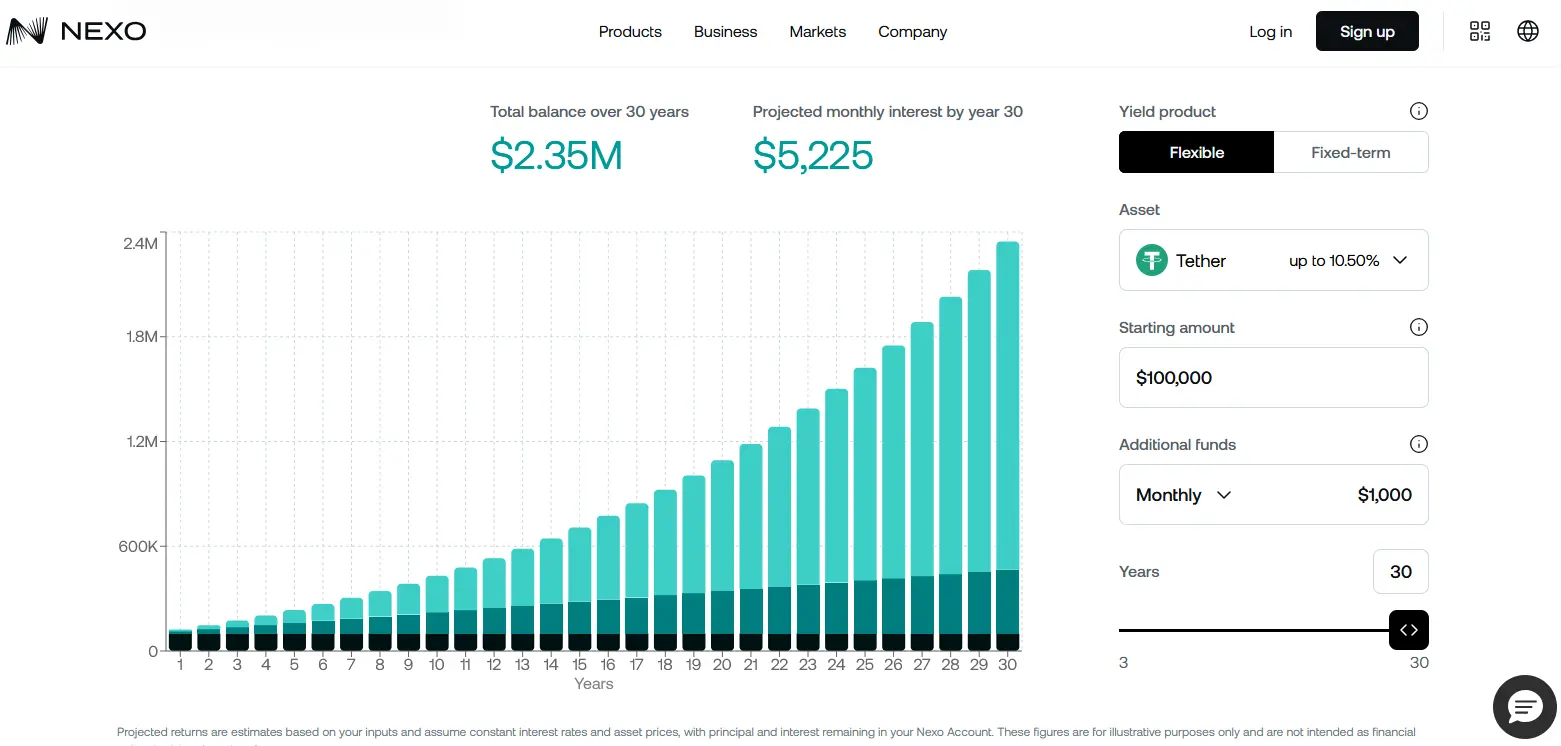
The final rate depends on your Nexo Loyalty Tier, selected term, and payout currency. Taking interest in NEXO tokens adds up to 2% to the standard rate. You can also schedule recurring purchases daily, weekly, bi-weekly, monthly, or yearly and fund them through supported methods such as ACH or wire transfers.
Nexo funds these returns through interest spreads on collateralized credit lines, transaction fees from exchange and payment services, and market-neutral treasury strategies. Clients holding at least $100,000 in digital assets get Nexo Private, with personalized onboarding and a dedicated relationship manager, and Nexo provides downloadable transaction histories and tax-reporting tools.
Nexo Savings Pros and Cons
What we like
- High stablecoin rates
- Daily interest payments
- Flexible and fixed plans
- Automated recurring purchases
What holds it back
- Loyalty tiers affect returns
- No public live PoR
6. Bitget Simple Earn
- Best for: RWA-backed savings products
- Savings type: Flexible and Fixed
- KYC: required
Bitget Simple Earn supports USDT, USDC, USDGO, U, USDe, USDS, and USTC through flexible and fixed-term products. Current rates reach approximately 6.92% APR on USDT and 6.66% on USDC, and the higher-rate offers come with subscription quotas.
Its Cash Plus product accepts USDT and USDC, pays up to 4% APR with daily compounding, and supports real-time withdrawals. Behind the scenes, deposited funds are converted into USDGO, whose reserves include short-term US Treasuries, Federal Reserve overnight reverse repurchase agreements, money market funds, and cash-management instruments held with federally chartered US banks.
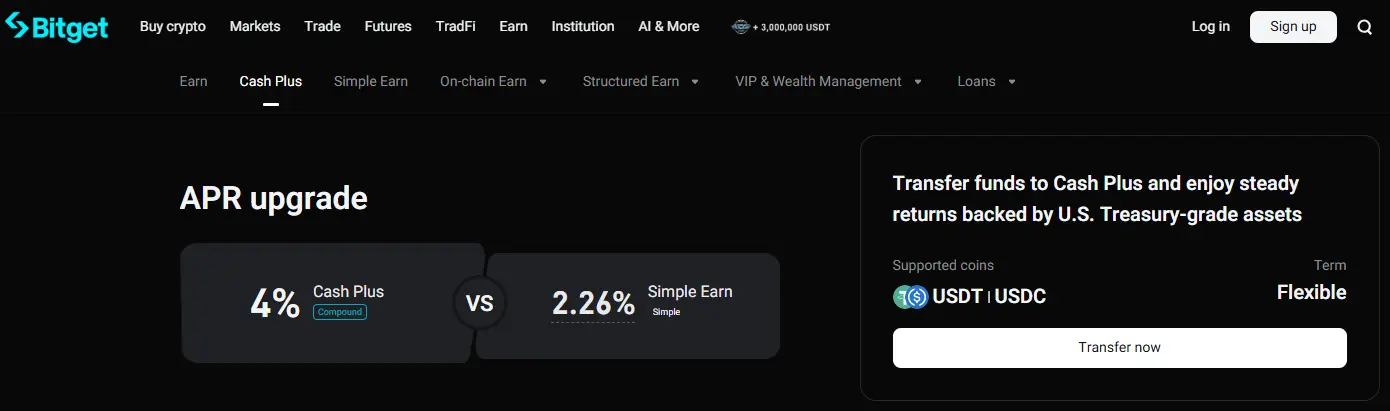
Bitget also offers BGUSD, which it describes as a principal-protected product paying around 3%. The label covers the product design, and issuer and platform risk stay with you. BGUSD is backed by a basket of real-world assets, including US Treasuries, and Bitget currently reports a 124.01% reserve ratio for it. USTC is listed too, and since it lost its one-dollar peg it belongs in a different category from the other supported stablecoins.
Bitget Simple Earn Pros and Cons
What we like
- Competitive USDT returns
- Daily-compounding Cash Plus
- RWA-backed BGUSD available
- Public reserve disclosures
What holds it back
- Higher rates have quotas
- Only USD-based stablecoins
7. KuCoin Savings
- Best for: USDG holders
- Savings type: Flexible and Fixed
- KYC: required
KuCoin Earn supports USDT, USDC, USDG, USDD, USDe, and U through flexible and fixed-term products. The comparison above uses the advertised USDG reference rate of up to 6% APR. Other assets have different rates, and some promotions apply only to a small qualifying balance. The KuCoin Earn page lists reference APRs, with different offers for each asset and term, and promotional tiers that apply to limited balances.
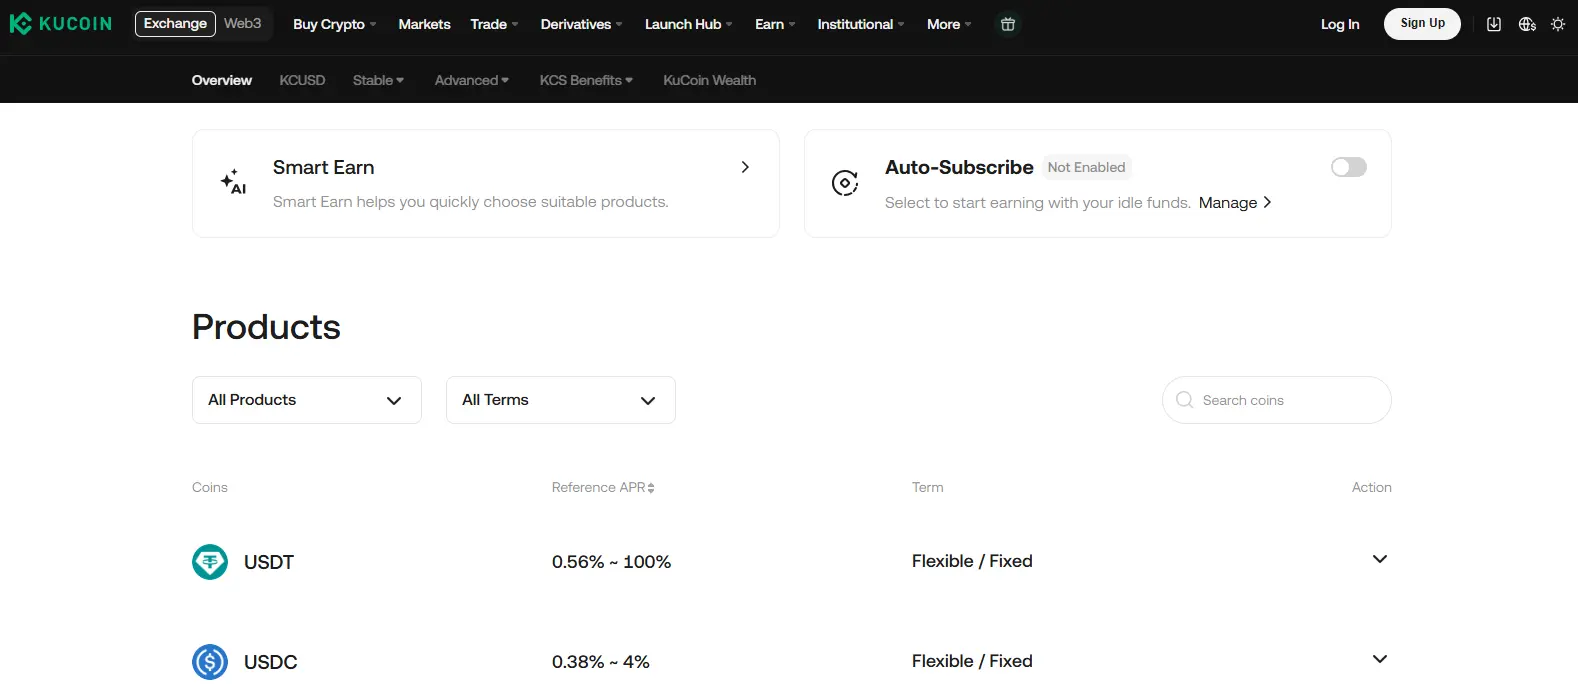
If you prefer to skip a separate Earn product, Hold-to-Earn pays rewards for keeping an eligible USDG balance once it is enabled, with the balance staying accessible. Check the current rate and eligibility in your account.
KuCoin also offers KCUSD, which it describes as a principal-protected Earn product with returns linked to tokenized US Treasury securities. The label describes the product design, and bank deposit insurance and platform risk are separate matters. Earnings accrue daily and are paid on the schedule in the product terms. KCUSD gives you another dollar-based earning option, with a different structure from regular flexible stablecoin savings.
KuCoin Savings Pros and Cons
What we like
- USDG Hold-to-Earn available
- Public Proof of Reserves
- Treasury-backed KCUSD available
What holds it back
- Low USDT and USDC returns
8. Bybit Easy Earn
- Best for: USD-based stablecoin selection
- Savings type: Flexible and fixed
- KYC: required
Bybit Easy Earn supports seven dollar-based stablecoins: USDT, BYUSDT, USDC, RLUSD, USD1, USDe, and USDTB. You place these assets in Flexible Savings to keep access to your funds, or pick fixed-term products for a stated period. Advertised returns reach up to 6.24% APY, and the available rate depends on the stablecoin, term, account eligibility, and subscription quota.
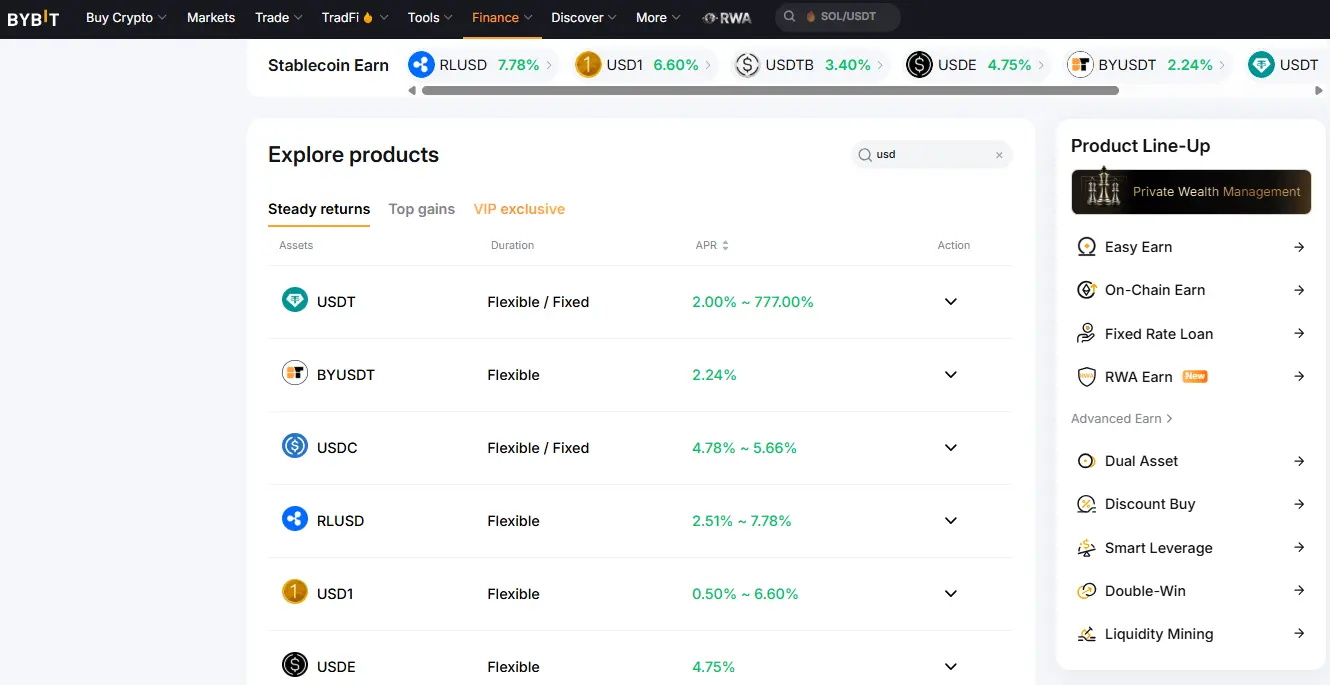
Rewards start accruing after a successful subscription and are credited under the conditions of the selected product. Every supported stablecoin is linked to the US dollar, so euro-backed and pound-backed options are missing. Bybit also has an RWA-backed Earn section, and those products follow different structures and carry additional issuer, liquidity, and underlying-asset risks next to regular stablecoin savings.
Bybit Easy Earn Pros and Cons
What we like
- 7 stablecoins supported
- Flexible and fixed products
- Public Proof of Reserves
What holds it back
- Only USD-based stablecoins
- Higher rates have quotas
9. Crypto.com Earn
- Best for: Existing Crypto.com subscribers
- Savings type: Flexible and fixed
- KYC: required
Crypto.com Earn supports USDT and USDC through flexible plans paying up to 0.50% annually. If you commit funds for up to 3 months, the rate rises to as much as 2% annually. USDP and DAI are supported too, through fixed-term allocations only. These products are open to users subscribed to an eligible Crypto.com membership plan.
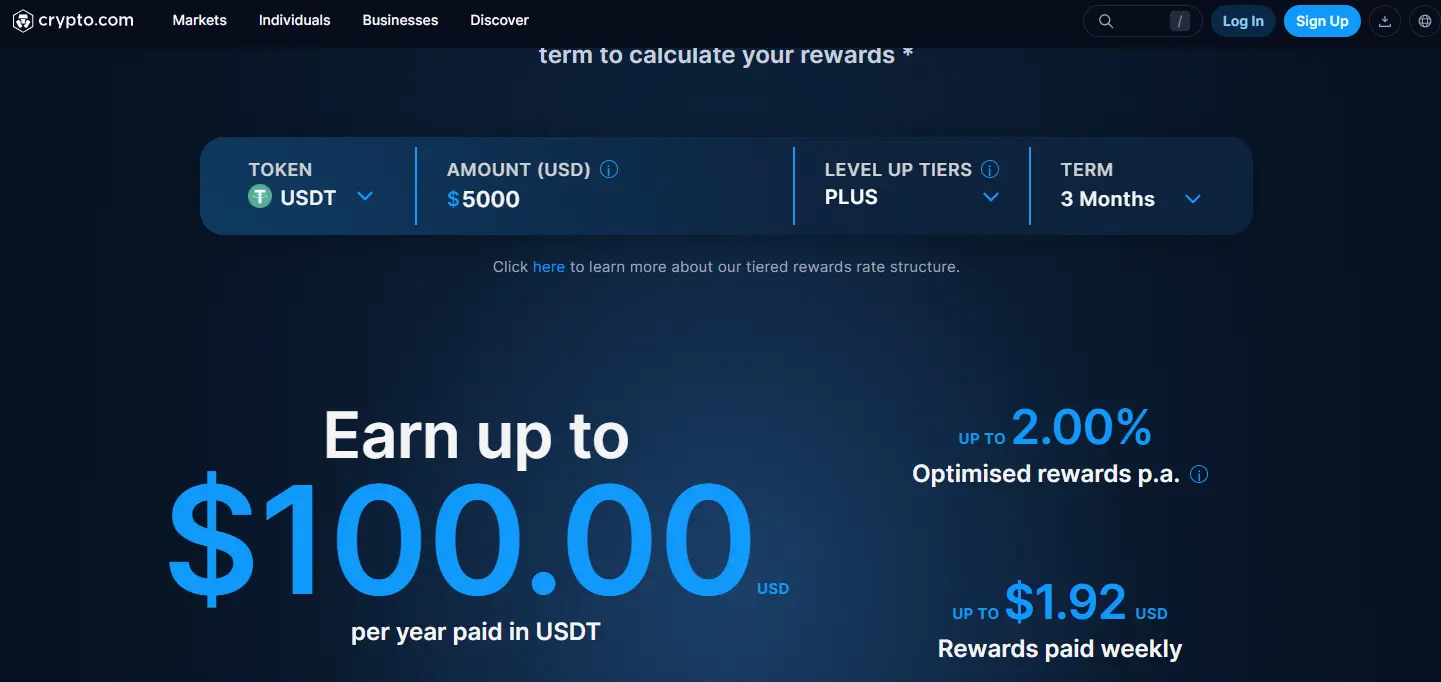
Crypto.com has also announced an upcoming cash rewards product paying up to 4.5% annually for Plus members, with higher rates planned for Pro and Private members. This product generates returns on fiat cash, a different thing from the stablecoin returns in Crypto Earn, and it is expected to come without a minimum balance or lock-up period. Crypto.com has yet to disclose its launch date, supported regions, or how the cash yield will be generated, so it stays outside the rate comparison on this page.
Crypto.com Earn Pros and Cons
What we like
- Flexible USDT and USDC
- Short fixed terms
- Daily reward accrual
What holds it back
- Paid membership required
- Flexible rates are low
10. Bitunix Easy Earn
- Best for: Earning without mandatory KYC
- Savings type: Flexible and fixed
- KYC: optional
Bitunix is an optional-KYC crypto savings account supporting USDT and USDC alongside other assets. Easy Earn includes flexible products you can redeem at any time and fixed terms of 7, 14, or 30 days. Flexible earnings are calculated hourly and added to the subscribed balance automatically.
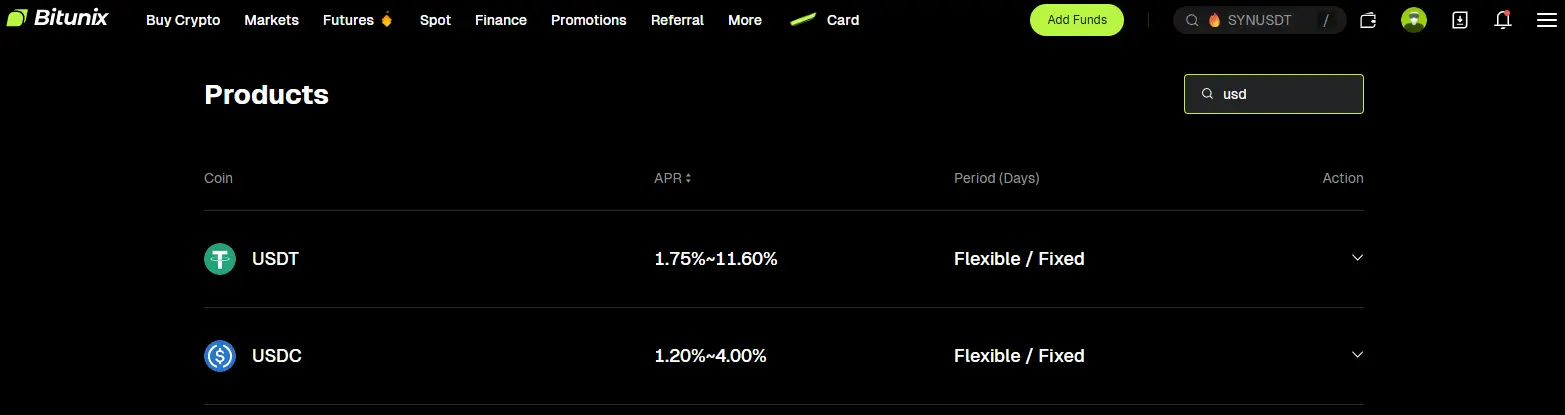
Rates and quotas are shown in the selected Easy Earn offer and differ by asset, term and account tier. Check how much of your balance qualifies for a promotional rate and what the remainder earns. Bitunix Card Auto Earn is a separate product, and its advertised 11.6% APR tier belongs to that product, with Easy Earn paying its own standard rates.
Bitunix lets unverified users access Easy Earn, with withdrawal limits in place, and identity verification can still be requested during account or compliance reviews. Product access also varies by jurisdiction.
Bitunix Easy Earn Pros and Cons
What we like
- Optional KYC
- Hourly interest calculation
What holds it back
- High APY has quotas
- VIP level affects rates
11. Sky sUSDS
- Best for: Self-custodial savings without KYC
- Savings type: Flexible and fixed
- KYC: No-KYC
Sky offers non-custodial stablecoin savings through sUSDS, currently the world’s largest yield-bearing stablecoin. You supply USDS and receive sUSDS, which accrues the 3.60% Sky Savings Rate automatically while staying liquid. The rate comes from Sky Protocol’s aggregate surplus, generated through protocol revenue across the whole protocol, with no single borrower, pool, or investment strategy behind it.
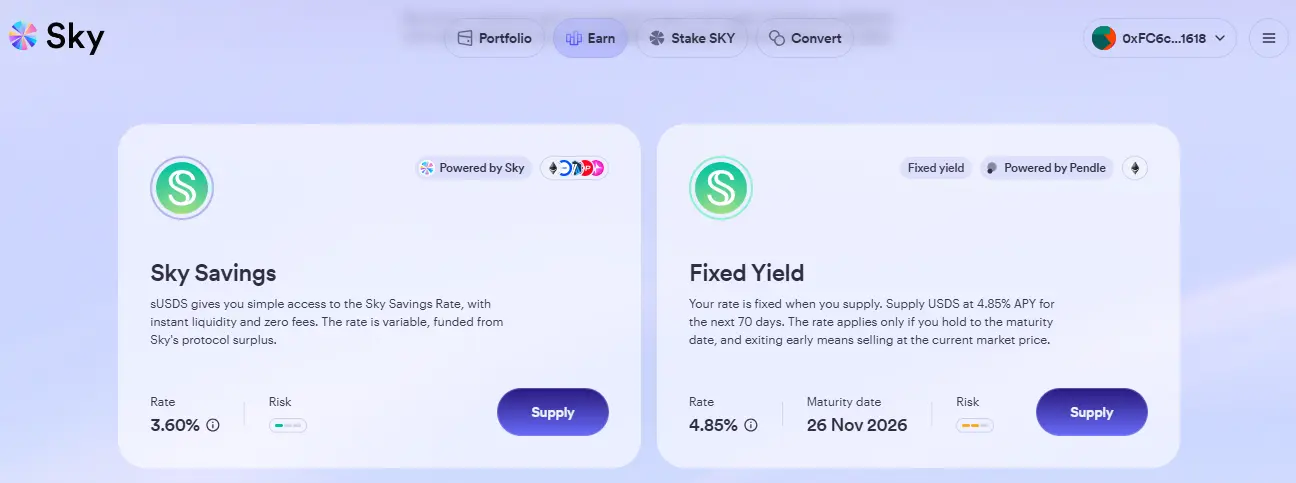
The rate is set through public onchain governance, and SKY token holders can raise or lower it. Sky also offers fixed yield through a Pendle integration, currently paying 4.85% APY when held until maturity. Exiting early means selling at the prevailing market price, which can be higher or lower than the original value.
Sky.money charges no entry, exit, or performance fee, and blockchain gas fees can apply. USDS backing, collateral levels, and governance changes can be verified onchain. The protocol uses overcollateralization and formal risk controls, and smart-contract and stablecoin risks stay.
Sky sUSDS Pros and Cons
What we like
- No KYC required
- Assets remain self-custodied
- Backing is publicly verifiable
- No platform yield fees
- Fixed yield available
What holds it back
- Only USDS supported
- Governance controls flexible rate
- Early fixed exits fluctuate
12. GRVT Earn on Equity
- Best for: Earning while actively trading
- Savings type: Automatic and flexible
- KYC: optional
GRVT Earn on Equity turns eligible USDT and USDC held across Funding and Trading balances into an automatic crypto savings account. Eligible users earn a variable base rate of 3.50% APY with no subscription, no locked funds, and no transfer into a separate Earn wallet. The balance stays available for trading, transfers, and withdrawals, and there is no maximum earning amount.
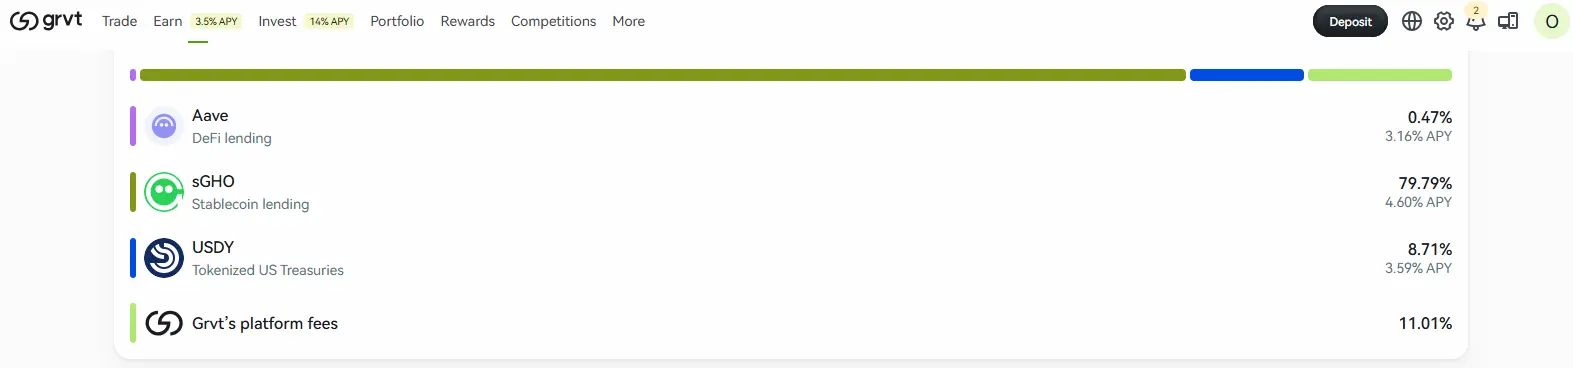
GRVT generates yield through third-party DeFi and real-world asset sources. Its current Earn on Equity terms cover USDT and USDC in funding and trading accounts, with daily payouts in USDT. Funds in Strategies vaults are excluded. The underlying protocols can suffer exploits, depegs or insolvency, so the quoted APY comes with your principal at risk.
Wallet-based access works without KYC, and GRVT can run compliance reviews or request identity information where necessary.
GRVT Earn on Equity Pros and Cons
What we like
- Earn while trading
- No balance limit
- No lock-up period
- Transparent yield sources
- Wallet-based access
What holds it back
- Yield paid only in USDT
- Underlying-protocol risk
Risks of Using Crypto-Saving Accounts
Crypto savings accounts can generate returns on idle stablecoins, and the balance is exposed to risks that a conventional insured savings account never carries.
- Platform insolvency: A provider may become unable to repay customer balances.
- Counterparty risk: Borrowers or investment partners may fail to meet their obligations.
- Stablecoin depegging: A stablecoin may lose its intended value against the dollar.
- Withdrawal restrictions: Platforms may delay or suspend redemptions during periods of financial stress.
- Smart-contract failures: Onchain savings products can lose funds through coding errors or exploits.
- Variable returns: Flexible APYs can be reduced without advance notice.
- Fixed-term limitations: Locked balances may be unavailable or penalized for early redemption.
- Regulatory restrictions: A product may become unavailable in a particular country.
- No deposit insurance: Most crypto balances lack the protection of bank deposits.
- Misleading advertised rates: The highest APY may apply only to a small balance or limited quota.
Tips to Choose a Cryptocurrency Savings Account
The highest advertised rate is one factor among several. A useful comparison considers how the return is generated, when funds can be accessed, and what protection exists if the provider runs into financial trouble.
- Check the effective rate: Calculate the APY that applies to your actual balance, beyond the advertised maximum.
- Understand the yield source: Identify whether returns come from lending, reserve income, Treasuries, or DeFi strategies.
- Review reserve evidence: Look for Proof of Reserves, liability reporting, financial audits, or onchain collateral data.
- Check withdrawal terms: Confirm lock periods, redemption times, early-exit conditions, and withdrawal limits.
- Assess the stablecoin: Review its issuer, reserves, redemption process, and previous peg stability.
- Consider account access: Check KYC requirements, supported countries, memberships, and loyalty tiers.
- Review the provider’s history: Look for security incidents, withdrawal suspensions, and previous customer losses.
- Check all costs: Include platform fees, performance fees, spreads, network fees, and subscription charges.
- Separate product risks: Flexible savings, fixed terms, tokenized Treasuries, and DeFi vaults carry different risks.
Is There Any Tax on Interest Earned From Crypto Savings?
Interest earned through crypto savings accounts can be taxable even when it is paid in stablecoins. In many jurisdictions, rewards count as income when they are credited to your account or become available for withdrawal. The taxable amount is generally based on the market value of the reward when received, and that value can also become the cost basis for a later sale, conversion, or payment.
If the asset is later sold above or below that value, a separate capital gain or loss can arise. Fixed-term rewards, automatic balance rewards, and DeFi savings can receive different treatment depending on local law. Keep records of reward dates, amounts, market values, and disposals, and check the rules that apply locally. For US readers, the IRS digital-assets guidance explains income reporting and disposals.
Bottom Line
If you came here looking for a crypto version of a traditional savings account, stablecoin products are the closest match. They pay a relatively steady return on assets designed to track fiat currencies, and flexible accounts keep the balance available for trading or withdrawal. Other assets are sometimes supported, and their price can move far more than the interest earned, which makes them a poor fit for the usual savings idea.
Crypto savings accounts are one way of generating returns. Our article on earning passive income with crypto covers staking, lending, liquidity farming, copy trading, and other methods. Those options can pay more, and they bring greater market, platform, and strategy risks with them.
FAQs
A crypto savings account lets you earn returns on stablecoins or other assets held with a platform. Depending on the product, rewards accrue automatically or require placing funds into flexible or fixed-term savings.
Crypto savings accounts carry platform, counterparty, stablecoin, liquidity, and smart-contract risks. Proof of Reserves, independent attestations, audits, and onchain collateral data improve transparency, and repayment and loss prevention remain separate questions.
Most crypto savings accounts sit outside bank deposit insurance. Some platforms carry insurance for specific custody or security incidents, which generally leaves insolvency, lending losses, and stablecoin depegging uncovered.
Yes. Losses can result from depegging, platform failure, lending defaults, withdrawal restrictions, or smart-contract exploits.
Yes. Flexible savings accounts generally let you redeem stablecoins whenever you need them. Coinbase, GRVT, and some Hold-to-Earn products also pay rewards on eligible account balances with no separate fixed-term subscription.
Returns come from lending, stablecoin reserves, US Treasuries, DeFi markets, transaction fees, or treasury strategies.
Usually, and some platforms apply processing periods, redemption limits, or temporary withdrawal restrictions.
Higher returns usually reflect stronger borrowing demand and greater platform, liquidity, counterparty, or stablecoin risk.